Insurance Claim Documentation · Photos, Scope, Adjuster Meetings
Roofing Insurance Claim Documentation in Fort Collins
After hail or wind, your insurer wants to know what happened to your roof and what it will take to fix it. We inspect, photograph and write a clear scope you can hand to your carrier. We do not adjust claims, and we never promise what your policy will pay.
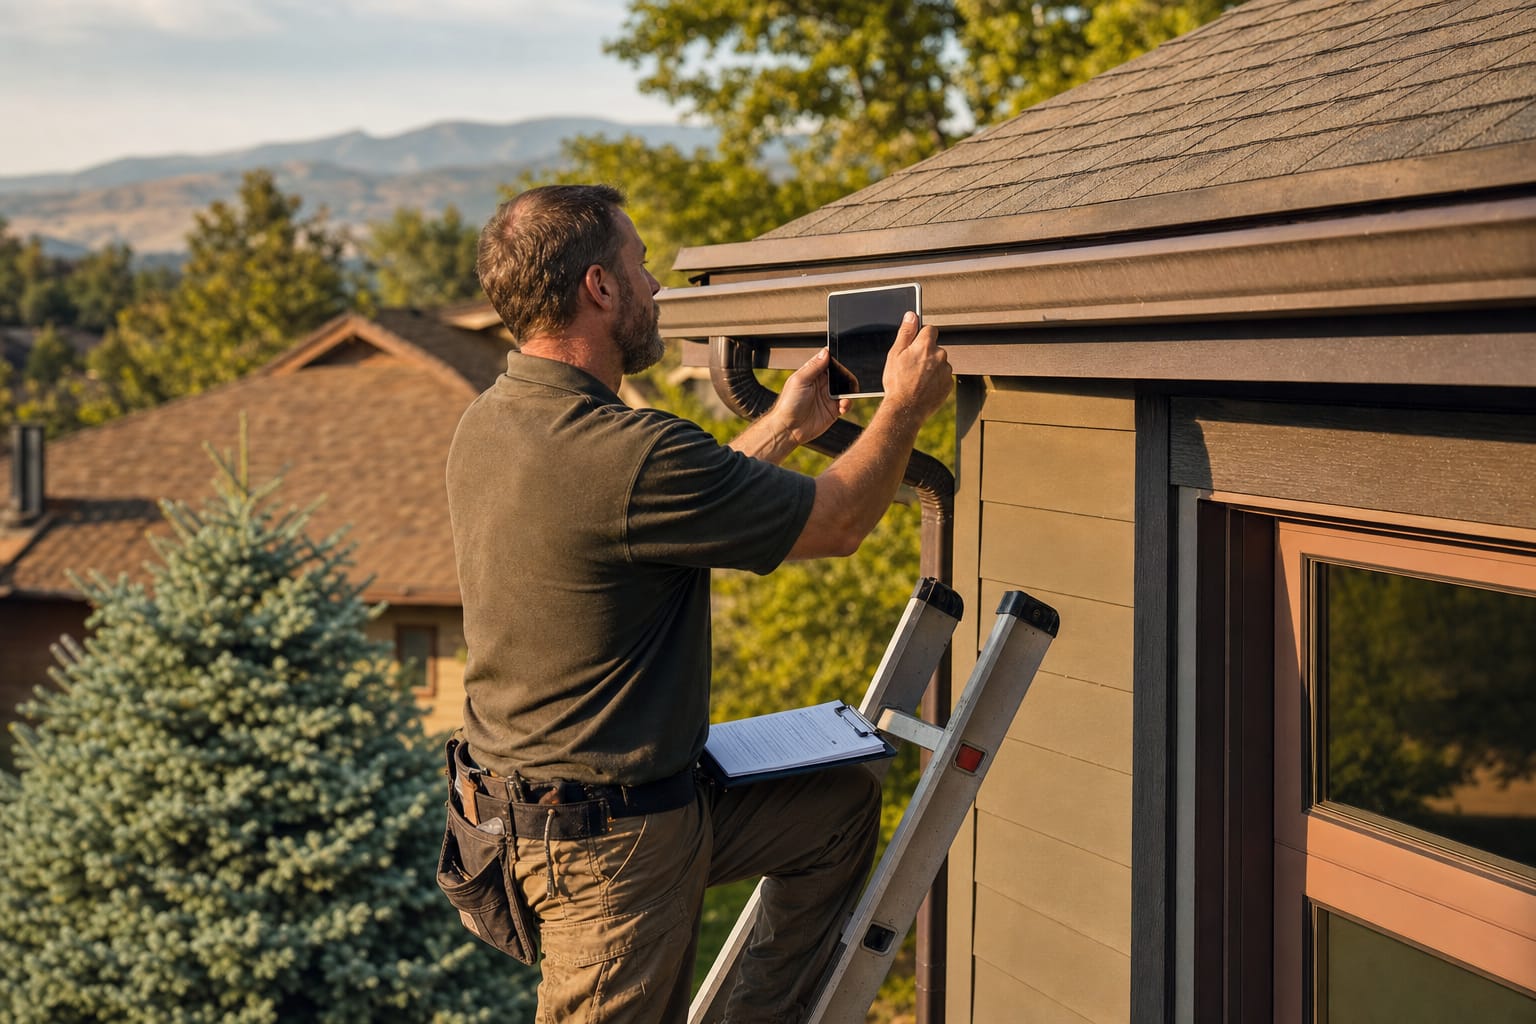
Fig. 01 Slope by slope photo record
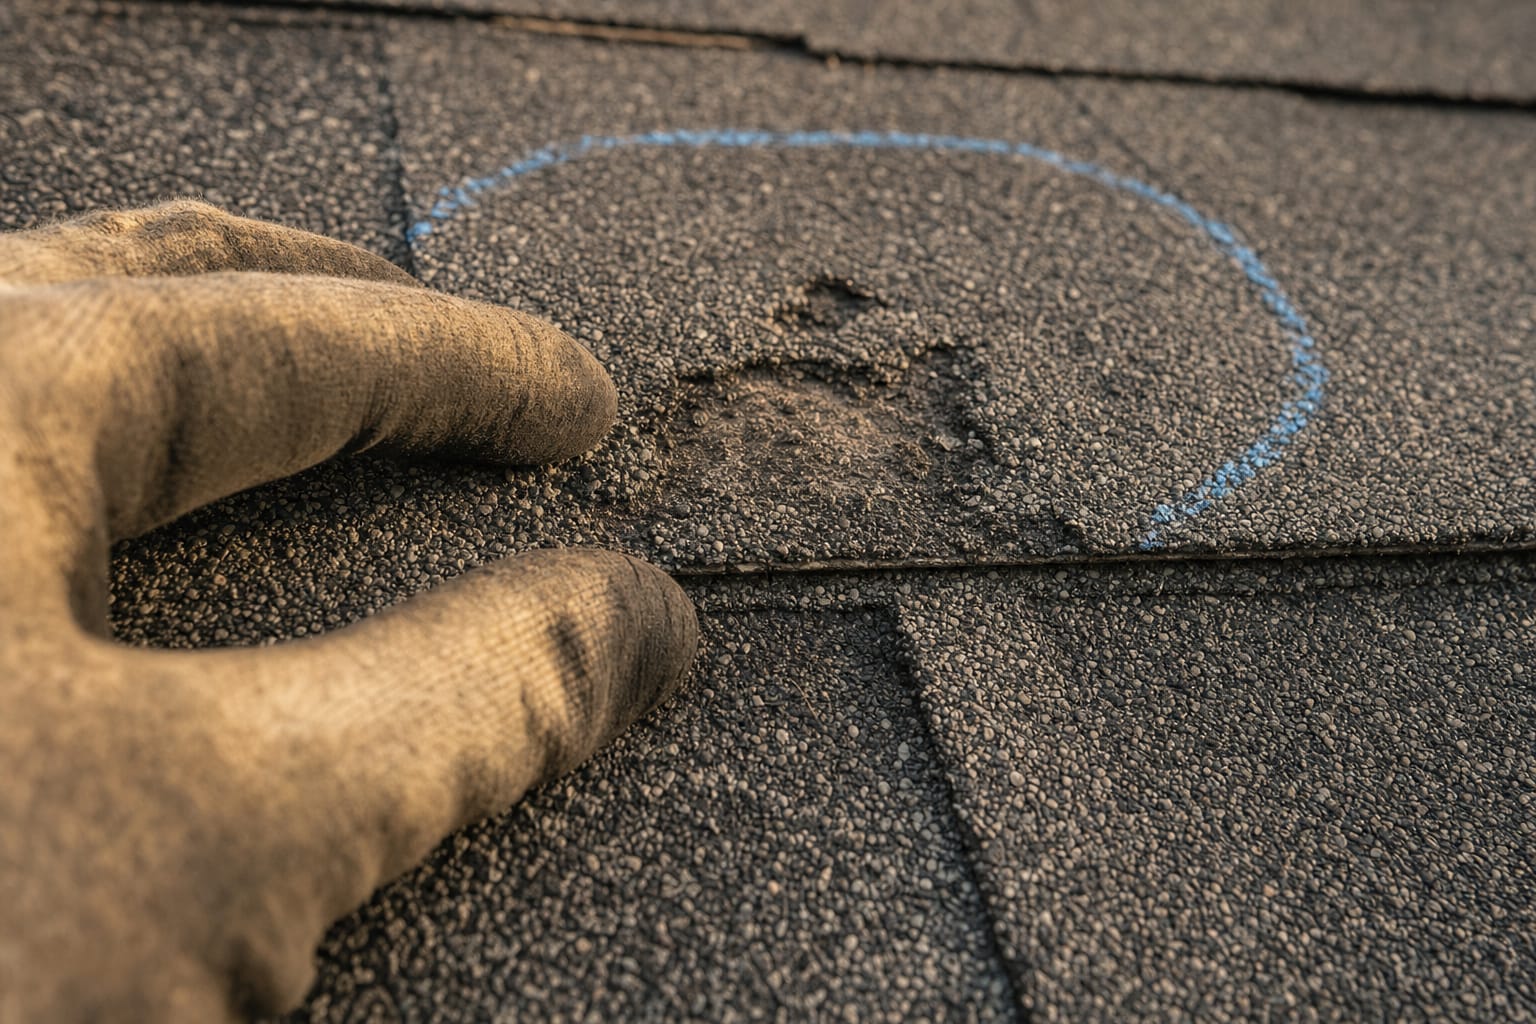
Fig. 02 Impact marks, chalked and photographed for the file
Our role, plainly
We document the roof. Your carrier decides the claim.
A roofing contractor and an insurance adjuster have different jobs. Ours is to give you an accurate, dated record of your roof’s condition and a scope of work priced the way we would price it for anyone. The adjuster’s job is to apply your policy to that record. We stay on our side of that line.
What we do:
- Inspect and photograph every slope, ridge, valley, vent, flashing and the siding below
- Write a clear, itemized scope of repair or replacement
- Meet the adjuster on site if you want us there, to point out what we found
- Compare our scope with the adjuster’s, line by line, and explain the differences to you
- Build the approved work and document completion
What we do not do:
- Interpret your policy or tell you what it covers. That is a question for your carrier or agent.
- Negotiate with your carrier on your behalf or act as a public adjuster.
- Waive, absorb or rebate your deductible. In Colorado it is against the law for a roofing contractor to do this, so a contractor who offers to “take care of the deductible” is offering something the law prohibits.
- Promise a claim outcome. Nobody can, and a contractor who does is guessing with your money.
Fresh storm damage starts on our hail and storm damage repair page. If you are not sure there is damage at all, a free roof inspection answers that before you call anyone.
How a claim moves
From first photo to final invoice.
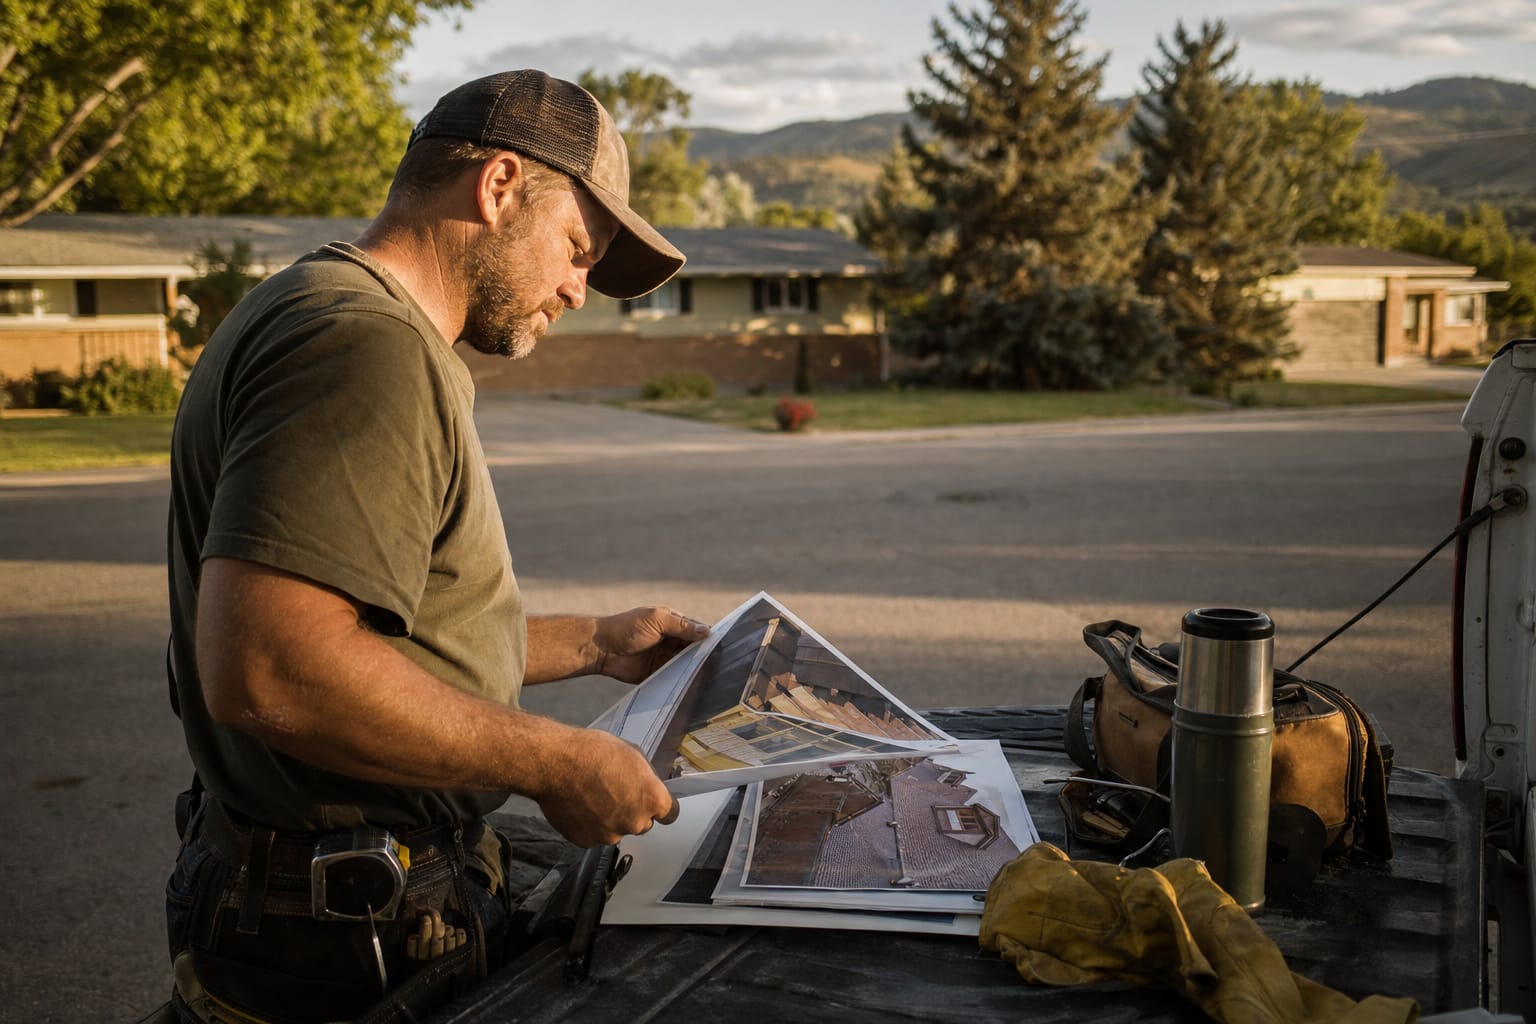
Fig. 03 Photo record reviewed before the scope is written
01
Inspect and document
We walk the roof and exterior, photograph the damage with the date on record, and put the findings and a scope in writing. The report is yours whether or not you file. That is how we work. If a crew knocked before you called anyone, read how to vet a roofer after a hailstorm.
02
You file with your carrier
You decide whether to open a claim, and you make the call to your carrier with your policy number and date of loss. If the report shows wear rather than storm damage, filing may not make sense. That is your decision, not ours.
03
Adjuster visit and scope reconciliation
Your carrier sends an adjuster. If you want, we meet them on the roof and walk them through what we photographed. Afterward we compare their scope with ours and explain any gaps to you in plain terms.
04
Approved work and completion documentation
Once you and your carrier have settled on a scope, we build it, whether that is a repair or a full replacement. You receive completion photos and a final invoice formatted for your carrier’s file, ready for whatever your carrier needs to close the claim.
Before the first call
What to have ready.
Policy number and carrier
Your declarations page has both, plus your deductible
Date of loss
The day the storm hit, as close as you can pin it
Ground photos
Dented vents, screens, siding, hail on the lawn. Stay off the roof
Prior roof records
Install date, past repairs, earlier inspection reports
Where we document
Fort Collins and across Northern Colorado.
Hail and wind do not stop at city limits. We inspect and document storm damage for homeowners in Fort Collins and the towns around it, and we come back for the adjuster visit.
- Fort CollinsHome base
- Loveland
- Windsor
- Greeley
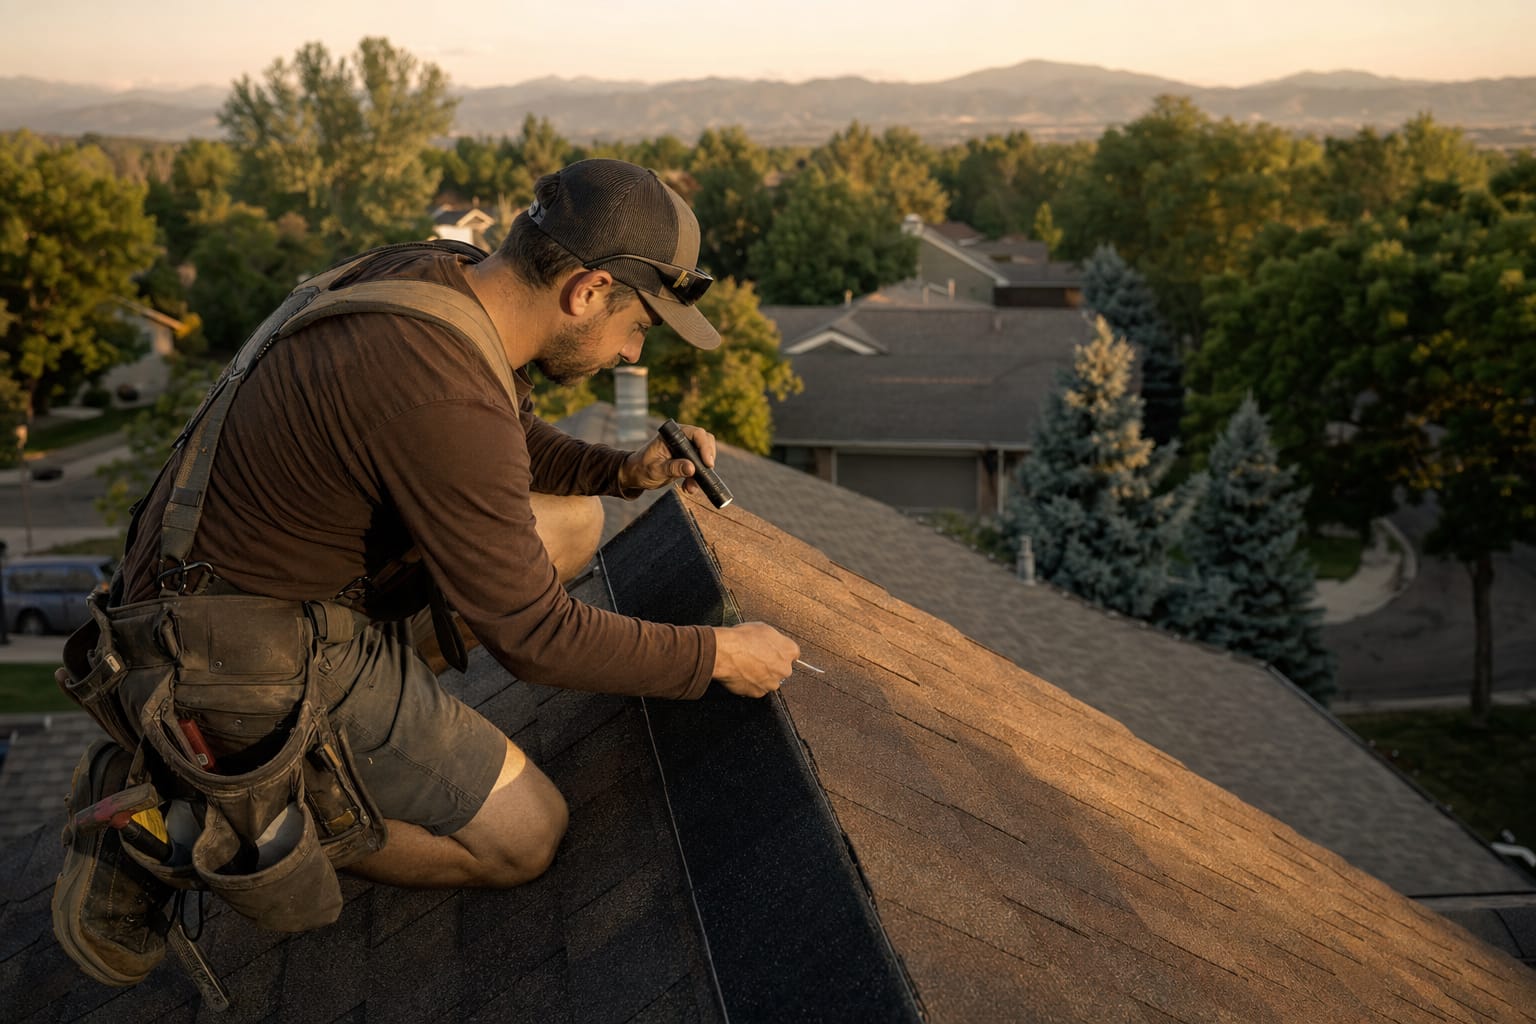
Fig. 04 Ridge line check after a spring storm
Claim questions
Straight answers about roof insurance claims.
How long do I have to file a roof claim after a storm?
Deadlines vary by policy and carrier, so read your policy or ask your agent as soon as you suspect damage. Get the roof documented promptly either way, because damage is easiest to attribute when it is fresh.
What is the difference between ACV and RCV?
Actual cash value (ACV) is what your roof was worth with age and wear subtracted. Replacement cost value (RCV) is what it costs to replace it today. With replacement cost coverage, the carrier may pay ACV first and release the difference after the work is done and documented. Your policy says which you have and how it pays.
Will my premium go up if I file a claim?
That depends on your carrier, your policy and your claim history, and we are not in a position to answer it. Ask your carrier or agent directly before you file.
Can I choose my own roofing contractor?
Your carrier may suggest contractors. Ask your carrier or agent what your policy says about choosing one. The Colorado Division of Insurance advises getting several quotes and working with Colorado-based contractors when possible, and whoever you choose should give you a documented inspection and a written scope before any work starts.
Will you meet the insurance adjuster at my house?
If you want us there, yes. We walk the roof with the adjuster and point out what we documented. We do not argue your claim or interpret your coverage.
Can you waive or cover my deductible?
No. Colorado law prohibits roofing contractors from waiving, rebating or absorbing an insurance deductible. You pay your deductible and we invoice honestly.
What if the adjuster’s scope is smaller than yours?
We show you exactly where the two differ and why, with photos. You can then ask your carrier for a re-inspection or a supplement. We provide the documentation, but the request comes from you.
Do I need to file a claim at all?
Not always. If the repair costs less than your deductible, or the damage is wear rather than storm related, filing may not help you. A documented inspection tells you what you are dealing with before you decide.